At a glance
Category
International Tax
Access
Free
Dr. Govind situated MAP within the larger context of tax certainty, a concept increasingly central to international tax policy and to India’s own domestic priorities. He outlined three pillars: (i) Dispute Resolution: MAP remains the core dispute resolution instrument. (ii) Dispute Prevention: He highlighted (i) APAs, ICAP, and joint audits and multilateral risk assessment tools. These aim to reduce disputes before they arise. (iii) Simplicity: Though difficult to define, he argued that simpler rules naturally reduce areas of conflict.
Using global MAP statistics, Dr. Govind identified key trends:
● MAP inventories continue to rise, partly a sign of trust and partly a sign of systematic pressure.
● Participation has expanded from 50 jurisdictions (2016) to 100+ jurisdictions today.
● Average resolution times are near, but not within the 24-month target.
● Transfer pricing cases achieve a high rate of bilateral resolution, while non-TP cases lag.
He previewed major OECD developments:
● A new MEMAP with 60 best practices and practical guidance.
● Work on non-TP APAs, encouraging pragmatic solutions despite policy disagreements.
● A project aimed at fostering dispute prevention within tax administrations, reducing recurring adjustments.
Dr. Govind concluded by emphasising MAP’s pragmatic value: even where legal principles diverge, competent authorities frequently find “middle ground” solutions that deliver effective relief from double taxation.
TaxTOC
More videos
Session 1: The Dawn of the Global 15% Minimum Effective Tax Rate Era and International Tax Developments in Indonesia, the Philippines and Vietnam
International Tax
Session 2: Origin, Tariffs and Controls - International Trade Developments in Indonesia, the Philippines and Vietnam
International Tax

Is There Really an International Tax System? | Prof David Rosenbloom on Pillar Two, Treaties & AI
International Tax · 12:02
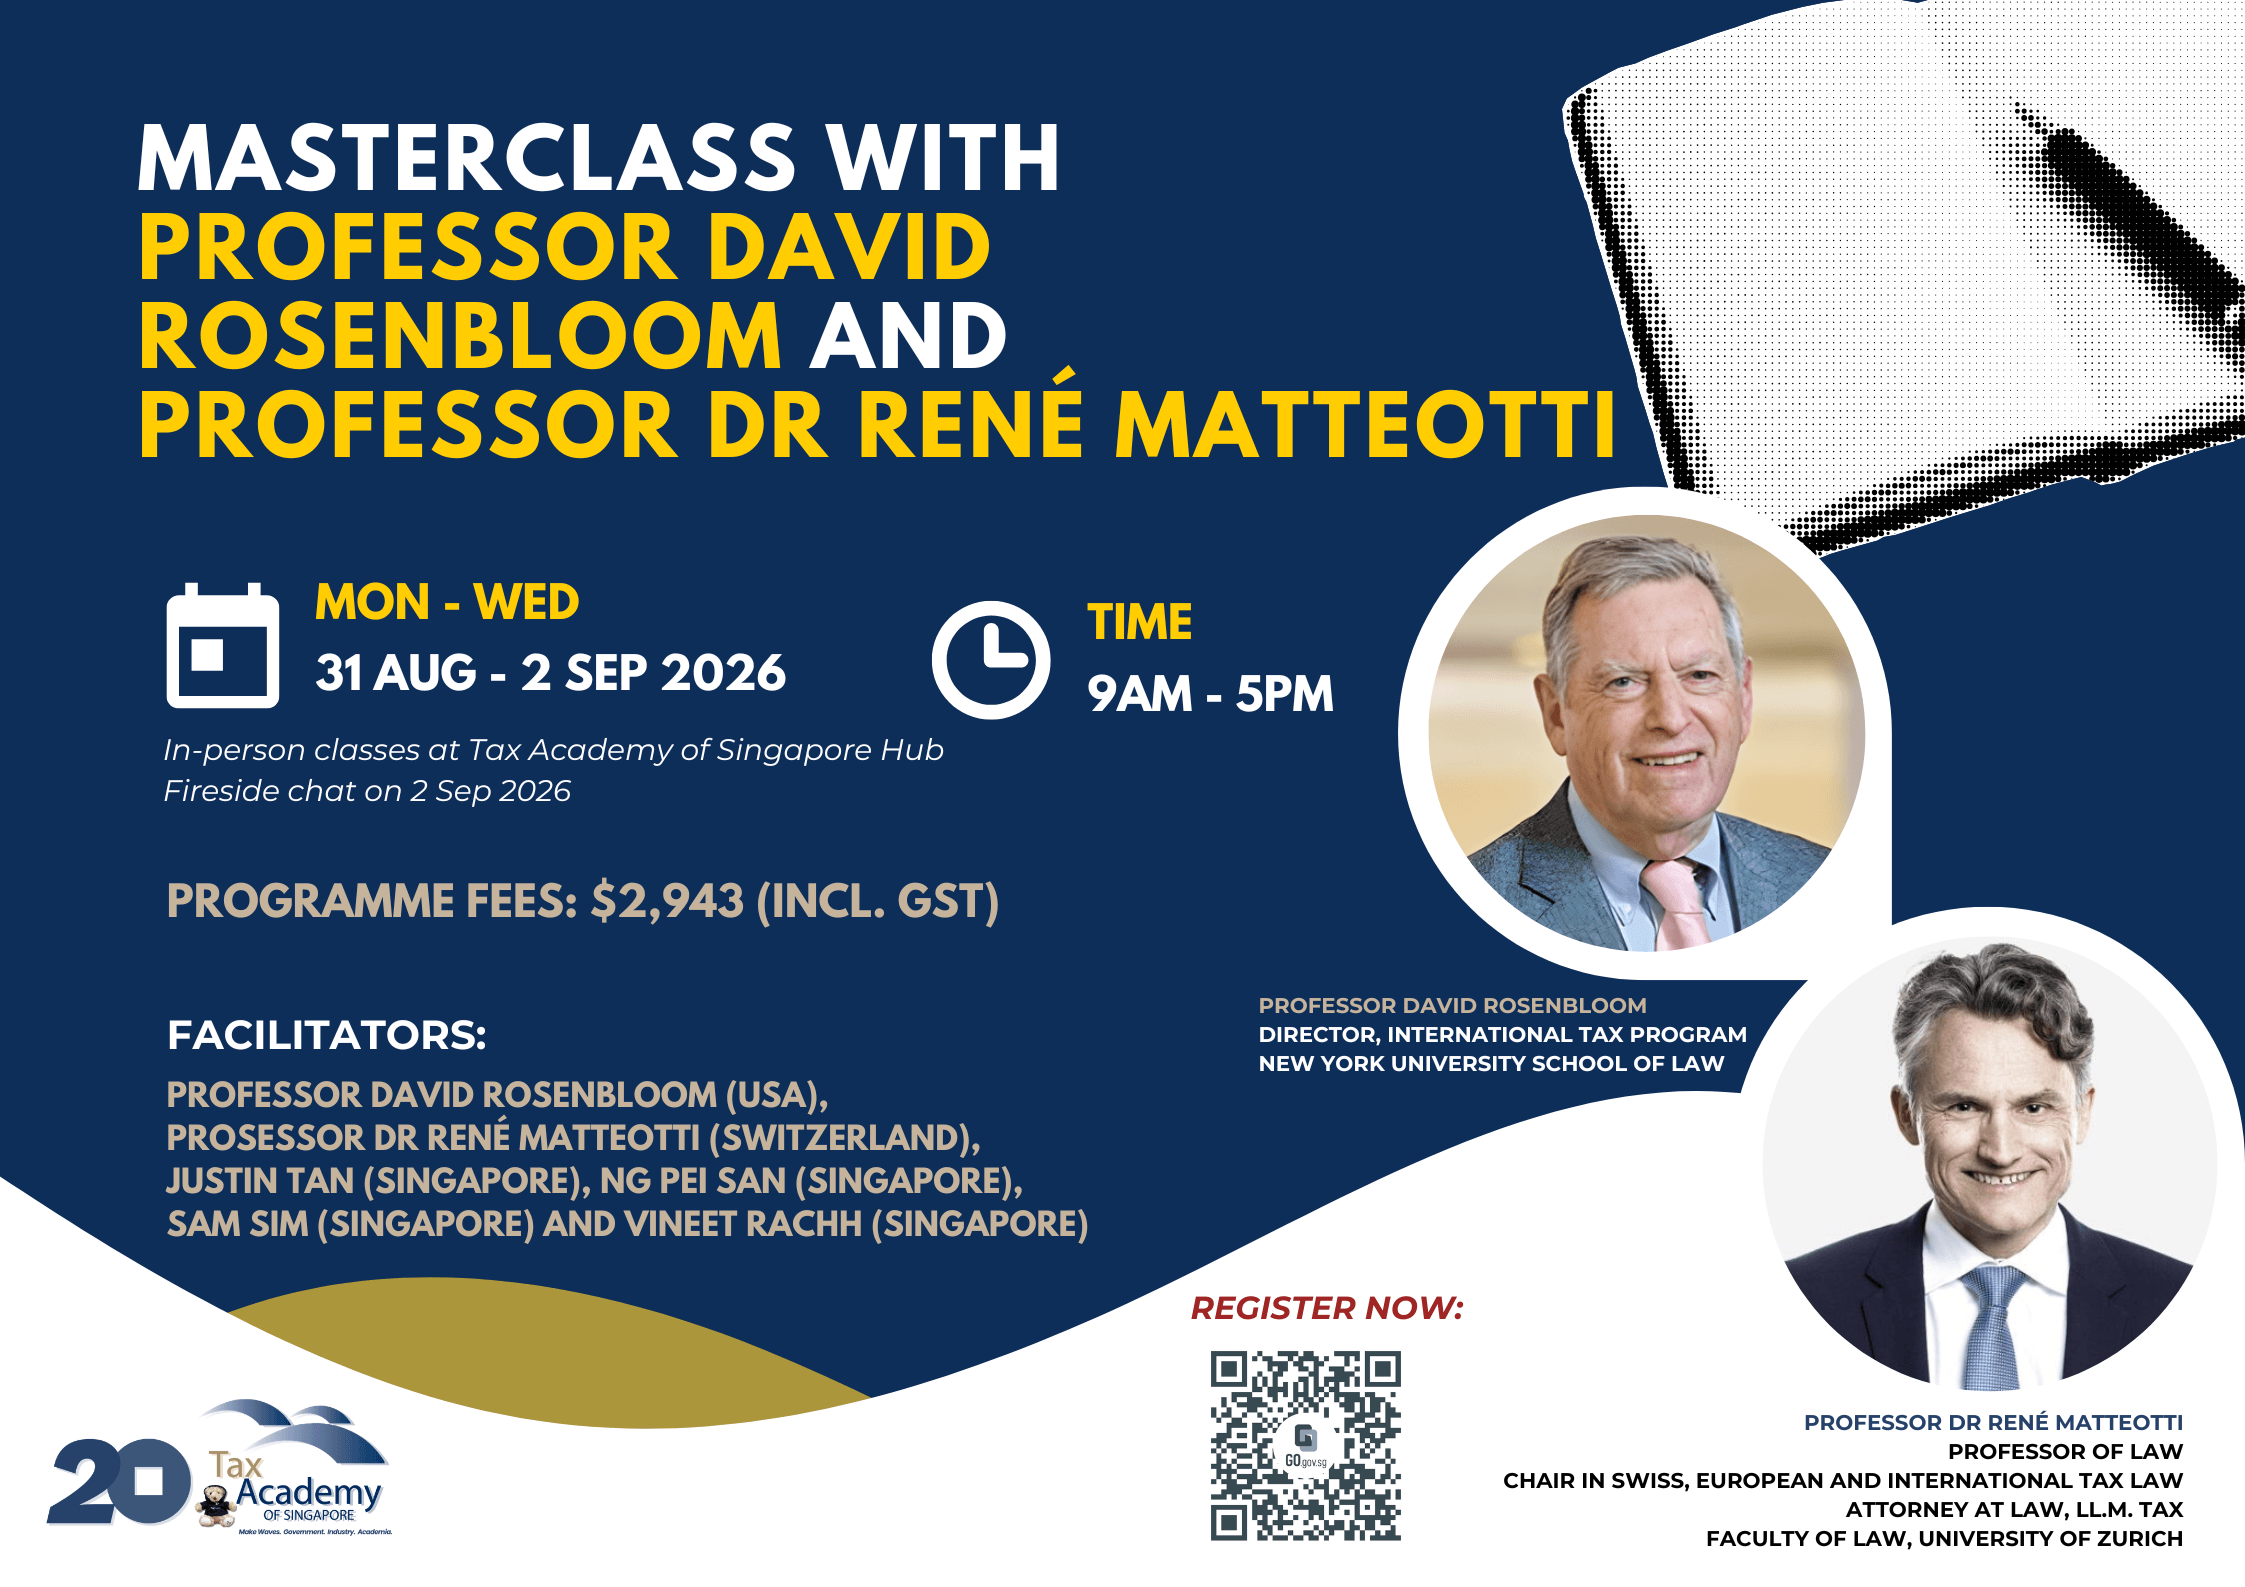
Session 4: Treaties – Foundations
International Tax · 3:37:26
Session 1: The Making of International Tax Policy
International Tax · 2:50:35

Module 5 - New International Tax Law Standards
International Tax · 2:13:30